Jake Wujastyk View Profile ↗
Jake Wujastyk Jake Wujastyk @Jake__Wujastyk
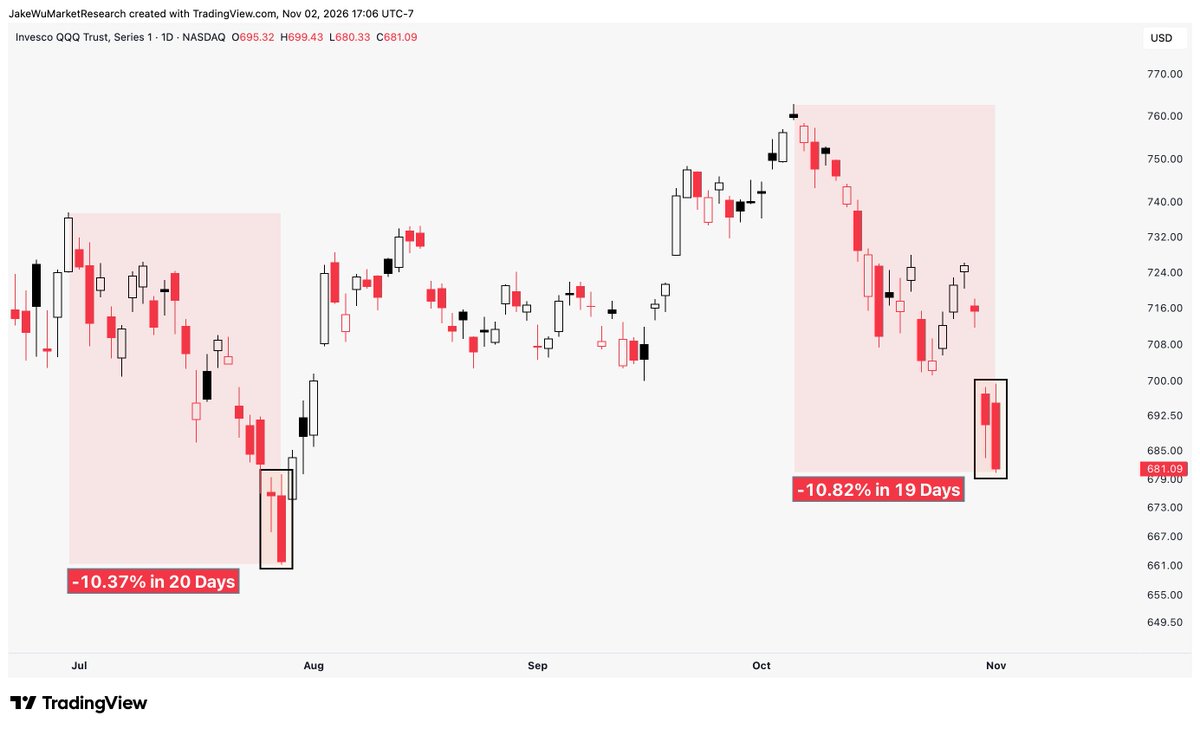
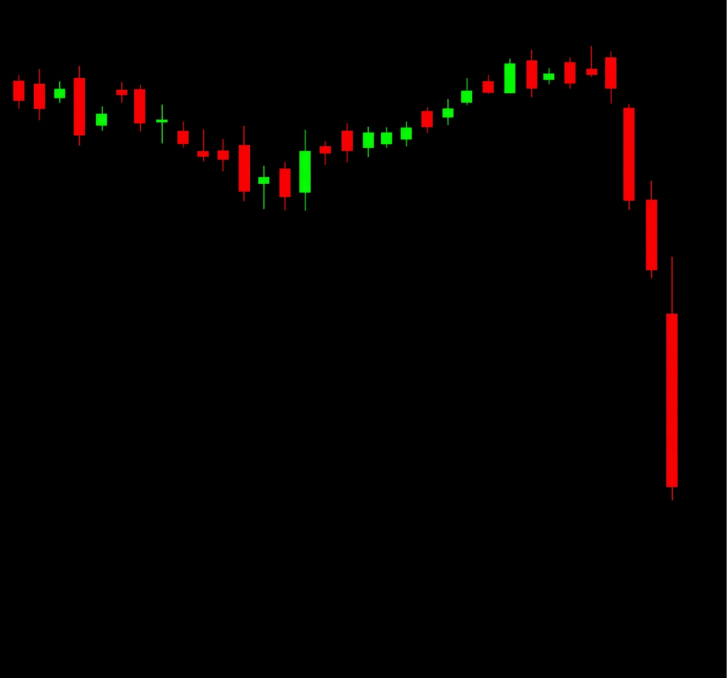
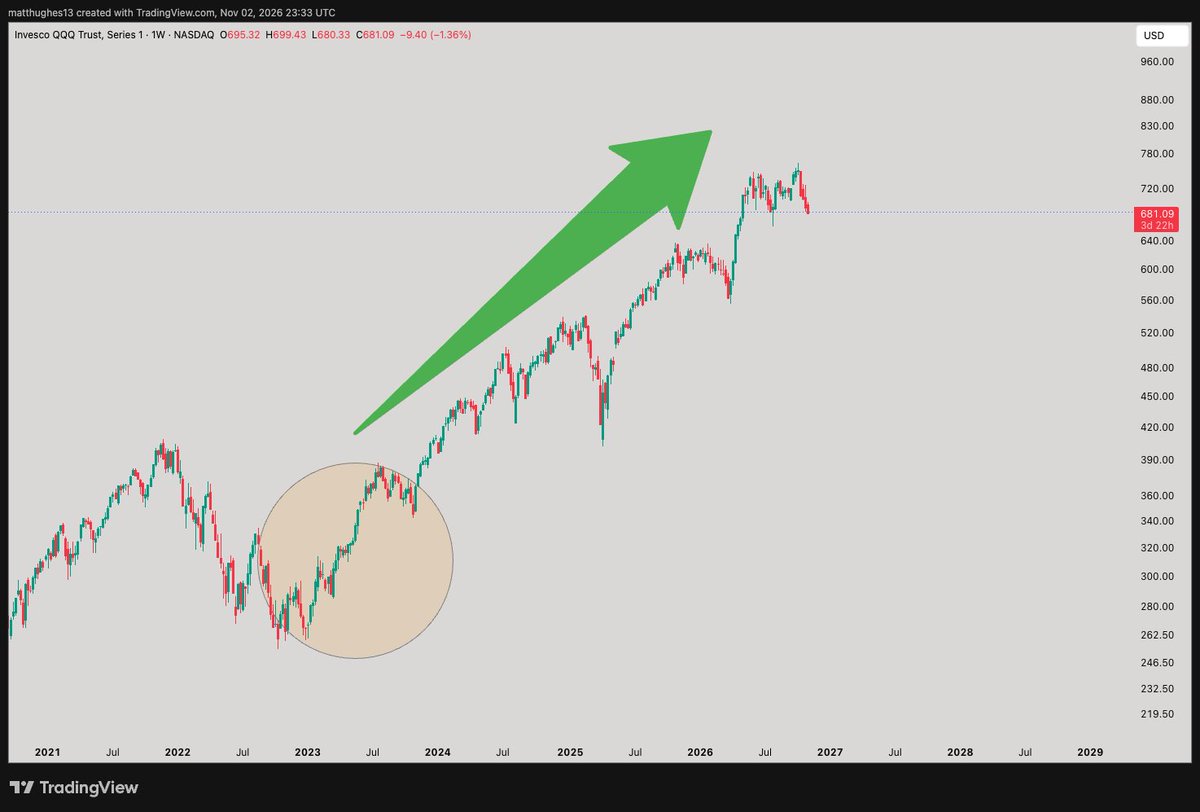
$QQQ $NDX $NQ_F Fun fact: This is the fastest 10%+ move down we have had since the April 2025 lows. The last three moves down similar to this (took longer) had very sharp snapback rallies within 2.5 weeks.
♥ 44 ⟳ 8 💬 14 👁 7.4k View →
Cantonese Cat 🐱🐈 View Profile ↗
❝ QT Nov 04 · 04:20 SGT 2.8h ago
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Happy 32nd Birthday to my dear friend Danny @dannycheng2022 the Whale Whisperer! Please join me in bombarding his timeline with birthday wishes and looking forward to seeing his continued success for years to come. 🥳🎉🎊 twitter.com/cantonmeow/status/198553855…
Cantonese Cat 🐱🐈 @cantonmeow
Quoting Nov 04 · 10:44 SGT · 364d ago
Happy Birthday to @dannycheng2022! He is officially 31 years old today. He probably won't be able to get through all of your Patreon or DM questions, but please join me with bombarding him with birthday wishes! 🪇🥂🎂🥳🪅🎈
Open on X →
♥ 142 ⟳ 1 💬 34 👁 10.6k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
This is literally a day to talk about anything else but the market and the AI trade. Either you were bearish yesterday and hope that you were right or stay quiet to get others to forget, or you were bullish and then you really should just shut the hell up for the rest of us.
♥ 125 ⟳ 2 💬 18 👁 11.7k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Before you invest Ask yourself this Is my wife happy? You can’t just believe in the narrative on the surface Otherwise you’d be deep in red if you didn’t buy her flowers on her birthday because “she doesn’t want to celebrate”
♥ 16 ⟳ 0 💬 5 👁 3.4k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Work decides to unleash a lot of fury on me today, so I won't be around much this morning. If you truly enjoy my content and what I do, I want you to go to any of @blondebroker1's post, comment😘or😉completely out of context, and give her a follow while you're at it.
♥ 7 ⟳ 0 💬 1 👁 1.5k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
I like feet. They help you balance and get you to places. I like women. You can look at them in the eyes, hear a different perspective, and learn from them. I like the market. It whips me when I least expect, calls me names, and gives me guilty pleasure that borderlines pain.
♥ 22 ⟳ 1 💬 5 👁 3.9k View →
❝ QT Nov 03 · 09:08 SGT 22h ago
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Where are the bond yield enthusiasts now? Did they all switch back to their foot fetish? twitter.com/cantonmeow/status/211036476…
Cantonese Cat 🐱🐈 @cantonmeow
Quoting Oct 14 · 21:39 SGT · 20d ago
I don't know anything. I'll tell you exactly what I think. I don't think 10 year yield is breaking out of this range. I think the more stocks crash and flush, the more impressive and longer lasting the next move up will be. I am acting accordingly with this thesis. You do you.
Open on X →
♥ 6 ⟳ 0 💬 2 👁 1.6k View →
❝ QT Nov 03 · 09:04 SGT 22h ago
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Somehow I still think Anthropic and Open AI will make trillions out of us before the AI narrative is truly over and before a real brutal and sustained bear market begins. twitter.com/cantonmeow/status/211200251…
Cantonese Cat 🐱🐈 @cantonmeow
Quoting Oct 19 · 10:06 SGT · 15d ago
The longer Anthropic and Open AI delay their IPOs, the more likely we are at the early stages of the AI theme. They'll use excuses like AI ethics, but I think they're just eyeing the right market conditions for a quick liquidity grab. I hope they don't go public in 2027.
Open on X →
♥ 14 ⟳ 0 💬 2 👁 2.2k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
$DOGE apparently sucks up the excess liquidity from economic expansion over the past 3 cycles and ran extremely close with ISM PMI. It usually has a delay with its run-up after PMI crosses 50. Either $DOGE is dead, or it's being extremely patient.
♥ 34 ⟳ 5 💬 7 👁 3.8k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
The Chinese market, as measured by the #HangSengIndex $HSI here, tracks ISM PMI extremely well. When PMI breaks above 50 convincingly, $HSI demonstrates some initial volatility for many months, followed by a powerful bull trend that tracks with economic expansion.
♥ 9 ⟳ 0 💬 3 👁 2.6k View →
❝ QT Nov 03 · 08:28 SGT 22h ago
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
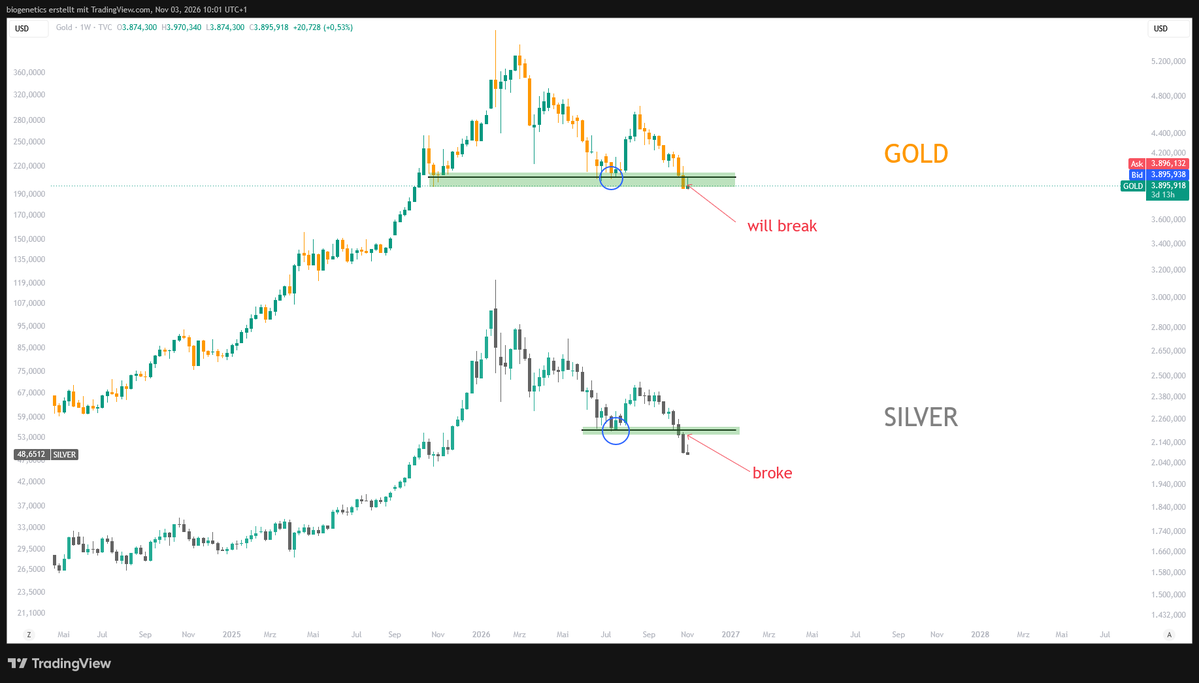
Silver bear market, just like gold, starts when economic expansion begins. Even though silver is at an attractive level and is bouncing off a key level at $49, I think there will be additional time to accumulate silver as economic expansion continues. twitter.com/cantonmeow/status/211741214…
Cantonese Cat 🐱🐈 @cantonmeow
Quoting Nov 03 · 08:22 SGT · 22h ago
Gold bear market starts when economic expansion begins. I think this is why the metal trade has been going horribly in 2026. It generally takes a few months to a year to rotate out of gold to more risk-on assets.
Open on X →
♥ 27 ⟳ 0 💬 3 👁 3.4k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
Gold bear market starts when economic expansion begins. I think this is why the metal trade has been going horribly in 2026. It generally takes a few months to a year to rotate out of gold to more risk-on assets.
♥ 30 ⟳ 1 💬 9 👁 4.6k View →
Cantonese Cat 🐱🐈 Cantonese Cat 🐱🐈 @cantonmeow
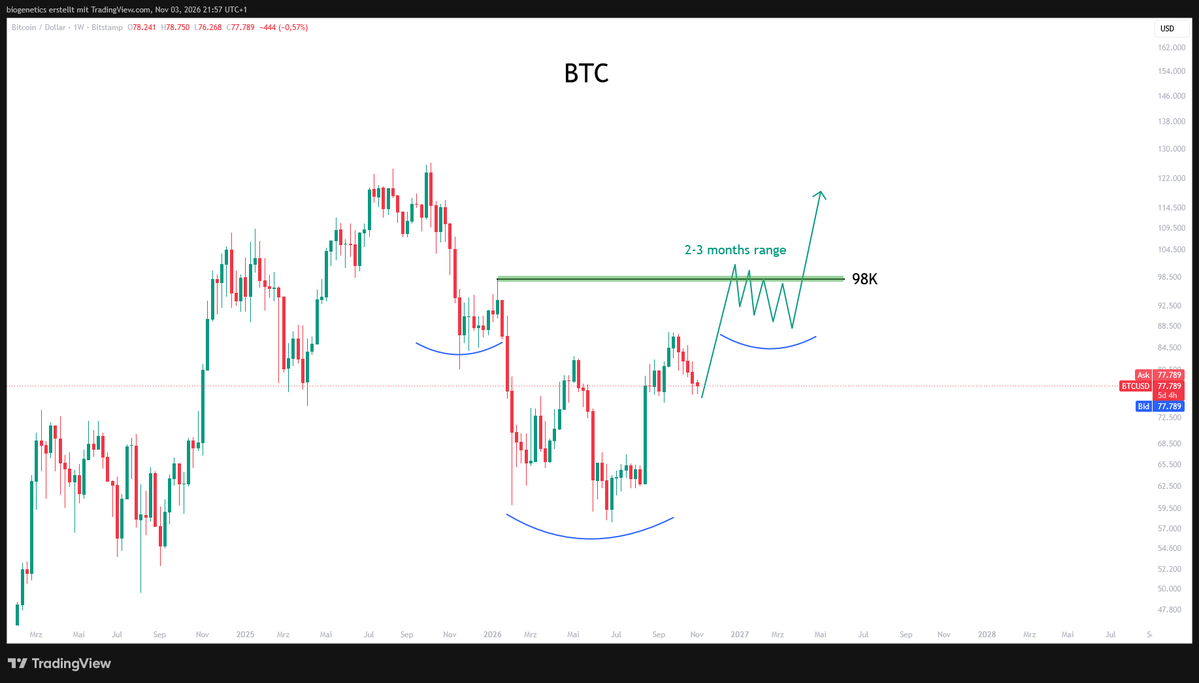
#Bitcoin follows the cycle of economic expansion and contraction, rather than a straight 4-year time line. The impact of #Bitcoin halving will become less and less over time as most of it is already in circulation and as derivatives by institutions are in play.
♥ 35 ⟳ 6 💬 10 👁 3.6k View →
chad. View Profile ↗
❝ QT Nov 04 · 05:19 SGT 1.9h ago
chad. chad. @chad_ventures
$AMD AMAZING numbers! Didn't expect anything else though. twitter.com/MentoviaX/status/2117727878…
MentoviaX @MentoviaX
Quoting Nov 04 · 05:17 SGT · 1.9h ago
$AMD Q3’26 EARNINGS HIGHLIGHTS 🔹 Revenue: $13.40B (Est. $13.09B) 🟢; +45% YoY 🔹 Adj. EPS: $2.09 (Est. $1.95) 🟢; +74% YoY Q4 Guide: 🔹 Revenue: ~$17B +/- 3% (Est. $16.23B) 🟢 🔹 Non-GAAP Gross Margin: ~55% Segment Net Revenue: 🔹 Data Center: $8.55B; +97% YoY (Est. $8.27B) 🟢 🔹 Client and Gaming: $3.70B; -8% YoY 🔹 Client: $2.95B; +7% YoY (Est. $3.03B) 🔴 🔹 Gaming: $773M; -40% YoY (Est. $634M) 🟢 🔹 Embedded: $1.11B; +29% YoY (Est. $1.07B) 🟢 Announcements: 🔹 Helios: Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running models on first AMD Helios rackscale solutions powered by MI450 GPUs and 6(th) Gen EPYC CPUs 🔹 HPE: Vultr will deploy first AMD Helios by HPE systems in a $12B deal 🔹 Versal AI Core XQRVC1902: space-grade SoC designed for missions lasting up to 15 years Other Q3 Metrics: 🔹 Non-GAAP Gross Margin: 56%; +200 bps YoY 🔹 Non-GAAP Oper Income: $3.92B (Est. $3.67B) 🟢; +75% YoY 🔹 Adj. EBITDA: $4.16B (Est. $4.02B) 🟢; +71% YoY 🔹 FCF: $554M (Est. $1.05B) 🔴; -64% YoY Comments: 🔸 “Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production.” 🔸 “Our fourth-quarter outlook reflects accelerating revenue and earnings growth, driven by strong demand across our Data Center portfolio.”
Open on X →
♥ 23 ⟳ 4 💬 3 👁 2.9k View →
❝ QT Nov 03 · 11:18 SGT 19h ago
chad. chad. @chad_ventures
Those words are EXACTLY what you want the CEO of the company you invested in to say. $PLTR A capable CEO is definitely required for entering a certain asset with size. Alex Karp is extremely smart, hard-working, and successful with his strategy. You know the saying…Never change a running system..
Tomislav Marinovic @DrTomsLens
Quoting Nov 03 · 06:52 SGT · 1d ago
Alex Karp on $PLTR's retail investors: “And to close, I just, you know, the people who invested in us early, many of them were investing their own money and, and would otherwise be called retail. And many now recently have reinvested in us. You know, the sovereign revolution is a metaphor for your interaction with Palantir. And the fact that we’ve been able to help you and you’ve been able to help us in your own wealth creation and in our journey and that you’ve defended us against what obviously now look like ridiculously stupid and malicious, incredibly hard to understand attacks is something that we will never forget. And part of the delivery here, part of what motivates me is helping to make sure we are fighting for you. And quite frankly, making sure that the people that made fun of you and made fun of us are suffering. And I’m very proud of that, and I’m very proud to have all of you along with us. And thank you for that support.”
Open on X →
♥ 2 ⟳ 0 💬 0 👁 527 View →
❝ QT Nov 03 · 07:54 SGT 23h ago
chad. chad. @chad_ventures
Wall St Engine @wallstengine
Quoting Nov 03 · 05:07 SGT · 1d ago
PALANTIR $PLTR Q3’26 EARNINGS HIGHLIGHTS 🔹 Revenue: $2.31B (Est. $2.18B) 🟢; +96% YoY 🔹 Adj. EPS: $0.44 (Est. $0.41) 🟢 🔹 US Commercial: $984M (Est. $943M) 🟢; +148% YoY 🔹 Adj. Op Income: $1.43B (Est. $1.26B) 🟢 Raises FY26 Guide: 🔹 Revenue: $8.530B-$8.534B (Est. $8.2B) 🟢 🔹 Adj. Op Income: $5.245B-$5.249B (Est. $4.76B) 🟢 🔹 Adj. FCF: $4.80B-$5.00B (Est. $4.52B) 🟢 🔹 US Commercial Revenue: >$3.6B Q4 Guide: 🔹 Revenue: $2.649B-$2.653B (Est. $2.46B) 🟢 🔹 Adj. Op Income: $1.640B-$1.644B (Est. $1.41B) 🟢 Revenue Breakdown: 🔹 US Revenue: $1.94B; +119% YoY 🔹 US Government: $953M (Est. $862M) 🟢; +96% YoY Other Q3 Metrics: 🔹 Adj. Oper Margin: 62% 🔹 Rule of 40: 158% 🔹 TCV: $2.92B; +6% YoY 🔹 US Commercial TCV: $1.46B; +11% YoY 🔹 US Commercial RDV: $6.52B; +79% YoY Key Updates: 🔸 Closed 212 deals of at least $1 million, 107 deals of at least $5 million, and 64 deals of at least $10 million Comments: 🔸 “The Sovereign AI movement is imposing the most dramatic dichotomy between haves and have nots that I have witnessed in 30 years of business. Every institution—government and commercial—is rapidly being forced, voluntarily or not, into one of these two categories,”
Open on X →
♥ 12 ⟳ 4 💬 5 👁 1.3k View →
Prof View Profile ↗
Prof Prof @TheProfInvestor
Everyone loves spreading fear or optimism about where the market is headed. But very few people are talking about the actual levels we need to reclaim before things improve. Here's what I'm watching: $QQQ: 700 first, then 713. $SPY: 760 first, then 765. The first level tells me buyers are starting to regain control. The second is where I'd feel more comfortable putting additional cash to work. If you're a Position trader- you dont need to predict the bottom. You need to recognize when the market starts repairing itself. Trade wisely everyone.
♥ 59 ⟳ 4 💬 10 👁 6.7k View →
Prof Prof @TheProfInvestor
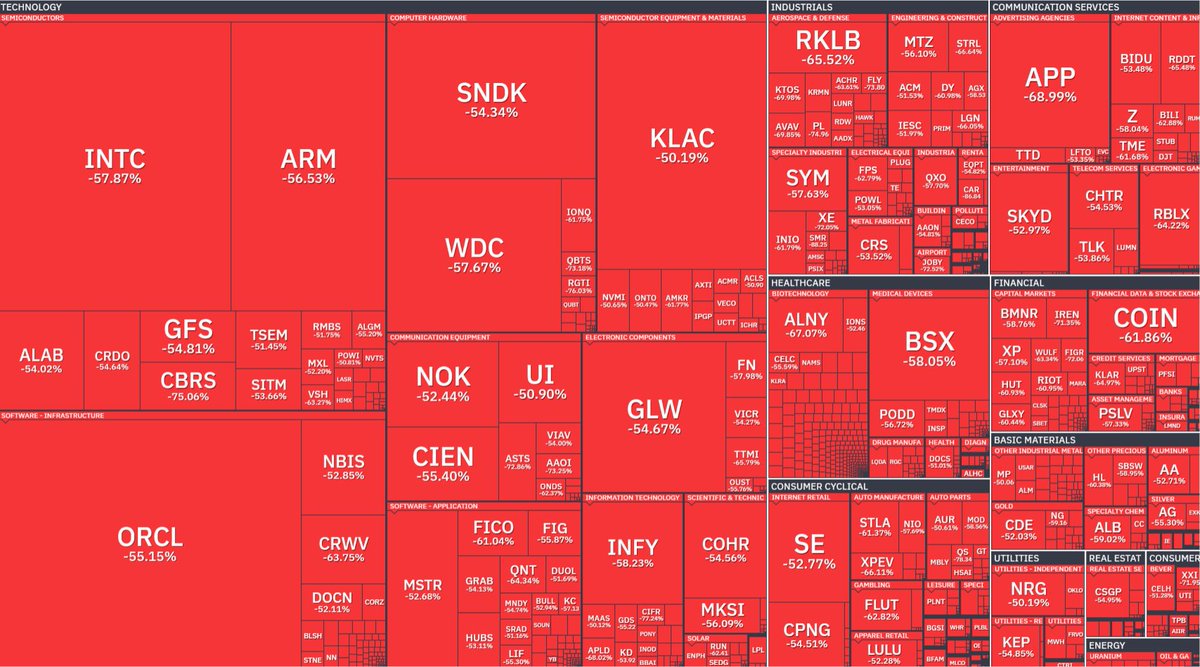
Nasdaq is at 200 Day Moving average. Nasdaq is now having its third 10% correction of 2026. 1000s Momentum stocks are now down 50-70%. Tech sentiment is awful. Absolute nutshow this year. $QQQ
♥ 69 ⟳ 1 💬 6 👁 9.9k View →
Prof Prof @TheProfInvestor
Intel in a literal free fall. Nobody should be buying this unless it can close above $70. Look for strength. This is coming from someone who called Intel at $38 $INTC
♥ 38 ⟳ 1 💬 6 👁 5.1k View →
amit View Profile ↗
amit amit @amitisinvesting
$AMD AMD DELIVERS A MASSIVE PRINT. Q3 2026 EARNINGS: - Revenue $13.4B, +45% YoY - Adjusted EPS $2.09, +74% YoY - Data Center Revenue $8.55B, +97% YoY - GAAP Operating Income $2.83B, +123% YoY - Adjusted Operating Income $3.92B, +75% YoY - Adjusted Net Income $3.47B, +77% YoY - Free Cash Flow $554M - Q4 Revenue Guidance ~$17B, +66% YoY AMD CEO Lisa Su: “We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year. With our leadership product portfolio and deep customer and supply chain relationships, we are confident in our ability to sustain very strong revenue growth and expanding profitability over the coming years.”
♥ 1.4k ⟳ 75 💬 67 👁 68.3k View →
amit amit @amitisinvesting
$PLTR Palantir TCV concerns are absolutely silly and the bears are becoming desperate. First, every analyst on the street increased their PTs. You usually don't have analysts, that react to price movements, increase their targets when the stock is going against their bullish call. This quarter was SO good that every single one of them ignored what the stock was doing and told their clients that they think it's going higher. Even Rishi from RBC (Motel 6) had to FINALLY raise his target into the $100s, upgrading Palantir from $90 to $130. You know the numbers were that good when Rishi has to upgrade by $40. Second, this 6% TCV YoY growth completely misses what management said during the call. "We signed multiple 8-figure deals in the quarter that were shorter in duration than usual, as customers rapidly adopted initial Sovereign AI capabilities in their enterprise," noted CFO David Glazer. This also explains why RPO was flat QoQ: "As a reminder, RPO is primarily comprised of our commercial business, as it does not take into account contracts with an initial term of less than 12 months and contractual obligations that fall beyond termination for convenience clauses, both of which are common in most of our government business." I mean the bears have really lost their minds to interpret low TCV and RPO growth as a reason why this quarter was bad. What Palantir is actually saying is they are signing customers that want to get started with deploying Sovereign AI ASAP. That means to get a shorter contract signed so the work can begin and as the value is created, those 8-figure deals can begin to expand out many years...because Palantir is not one of those companies that will get paid and deliver nothing. If anything, I see it as a sign of incredible strength that management is willing to sign contracts on a shorter term basis and immediately begin proving how transformational the Sovereign movement can become and earn their ability to extend those contracts. The fact that the top average revenue per top 20 customer is up from $83M a year to $146M a year, +76% YoY, shows how much value this company is creating and why net dollar retention is now 165%. Customer count at 1090 customers is EXCITING, not a red flag, this is a company that is growing FASTER and more efficiently than any other software company on the planet, and doing so with less than 1100 customers...you would have to genuinely be desperate to think that that is bearish when in reality that means the relationships they have with their partners are truly transformational and they aren't just signing customers to sign them but rather every time they get someone in the door, they can keep them for a VERY long time and monetize that relationship better than any other software company because that customer is actually receiving the value they pay for. Bears, you need a better bear case to take down one of the single greatest companies the market has ever seen. Please, try harder.
♥ 658 ⟳ 52 💬 68 👁 57.2k View →
amit amit @amitisinvesting
$PLTR Palantir, once again, puts up one of the best quarters that the market has ever seen. Being able to grow revenues 96% while having 62% adjusted operating income margins is unheard of. There is no other software company that is even close to putting up these types of results. US commercial revenue officially passed US government revenue for the first time. I remember in 2022, the bear case was centered around the company being too reliant on the USG. If anything, that was the bull case because that gave them the time to figure out how to scale US commercial and now we have a company doing 29% growth QoQ, which would be amazing YoY for most companies as Dr. Karp said, but also scaling that YoY growth at 148% for US commercial. It is unprecedented. So, why? Why is it happening? Well, it seems like Sovereignty is a very, very big deal. “The Sovereign AI movement is imposing the most dramatic dichotomy between haves and have nots that I have witnessed in 30 years of business. Every institution—government and commercial—is rapidly being forced, voluntarily or not, into one of these two categories,” said Alex Karp. Having been to multiple AIPCons and Institutional Sovereignty bootcamps this year, I can say that this is very real. When you talk to customers, you realize that they want much, much more than just plugging their enterprise into an LLM. They actually want FDEs, they want the grunt work of figuring out how to build custom workflows, they want the post training and fine tuning of open models...they want outcomes. The reason Palantir is growing this fast and continuing to show so much operating leverage is because they are delivering outcomes. That's why this is working. The company is doing this with 1090 customers. Most enterprise software companies at this scale have well over 100K customers. I mean, once again, this is unprecedented. Their net dollar retention scaled to 165%...their rule of 40 is now a new record at 158%...these are numbers that you only get when the company's entire mission is geared towards making sure their partners succeed and as a result, they are being paid for that value and then monetizing that value at the highest efficiency any software company ever has before with these margins. Stock is down due to macro, midterms, etc. but the core business is growing faster than anything we have ever seen and doing so in one of the most profitable ways ever. Their adjusted FCF in 90 days is now equal to the revenue they were bringing in early last year. An incredible quarter by Palantir, congrats to all shareholders and a deep thank you to the executive team and employees.
♥ 296 ⟳ 16 💬 26 👁 21.0k View →
amit amit @amitisinvesting
$GRAB Grab had an exceptional Q3. - $1.12B of revenue, the first billion dollar quarter - 57M monthly users, fastest QoQ growth since 2022 - EBITDA margins now highest in history of the company at 21%, up 565 basis points YoY - Raised EBITDA guide from 45% growth to 60% growth YoY - Total quarterly active advertisers on self-serve platform grew 39% YoY, and average spend of these advertisers grew 13% YoY - Adjusted FCF now $533M, doubling YoY - Financial services is now profitable - Bought back $400M of stock, CEO bought $30M himself. 11B marketcap, 5B in cash, doing $4.2B of revenue and growing the bottom line 60%. Listening to the call, looks like Meta chose Grab to be one of the first partners to integrate with Muse in Singapore. It is not easy for a company to do $1B in revenue every 90 days and it is also not easy to have 7% of the entire SEA population using your products, while growing that number 20% YoY. Network effects compounding with operating leverage is the simple thesis, unfortunately oil has been the headwind but this was an outstanding quarter for the company.
♥ 152 ⟳ 18 💬 15 👁 17.9k View →
amit amit @amitisinvesting
A TON OF THINGS HAPPENED IN THE STOCK MARKET TODAY. Here's a full recap: 1. Palantir $PLTR delivered an extraordinary Q3 2026, with revenue surging 96% YoY to a record $2.31B, marking its first quarter above $2B, while U.S. commercial revenue skyrocketed 148% YoY to $984M, surpassing U.S. government revenue of $953M for the first time in company history. Total U.S. revenue grew 119% to $1.94B, while adjusted EPS reached $0.44 and GAAP net income climbed to $1.13B. Profitability remained exceptional, with adjusted operating income of $1.43B, representing a 62% margin, and adjusted free cash flow of $1.22B, representing a 53% margin. Palantir achieved a remarkable Rule of 40 score of 158%, closed 64 deals worth at least $10M, and grew U.S. commercial remaining deal value 79% YoY to $6.52B. Management also significantly raised FY2026 revenue guidance to $8.53B, representing 91% annual growth, while projecting U.S. commercial revenue growth of at least 143% and adjusted free cash flow of $4.8B–$5B. CEO Alex Karp emphasized that the accelerating sovereign AI movement is creating unprecedented demand for Palantir's AIP, Foundry, and Ontology platforms, as governments and enterprises increasingly seek to deploy AI using their own proprietary data and infrastructure. 2. Meta $META and Oracle $ORCL are preparing major capital raises as the world's largest technology companies continue securing funding for their expanding AI infrastructure investments. Meta is reportedly targeting at least $20B through a U.S. dollar- and euro-denominated bond offering, potentially spanning five dollar tranches and six euro tranches, with Citigroup $C and Morgan Stanley $MS coordinating investor calls. Meanwhile, Oracle is reportedly preparing a nearly $10B equity offering at an approximately 11% discount, alongside a six-part U.S. dollar investment-grade bond offering and a newly filed mixed shelf registration. Fitch estimates Oracle's combined capital raise at approximately $20B, including $10B in equity. 3. Grab $GRAB delivered strong Q3 2026 results, with revenue increasing 27% YoY to $1.11B and adjusted EBITDA surging 73% to a record $237M, while its adjusted EBITDA margin expanded 565 basis points to 21.3%. Monthly transacting users reached a record 57.2M, up 20% YoY, as Grab added 3.3M users during the quarter, its strongest quarterly addition since Q1 2022. On-Demand GMV grew 18% to $6.84B, while Financial Services revenue surged 124% to $201M, with the segment achieving adjusted EBITDA profitability for the first time at $12M. Grab also raised its FY2026 revenue guidance to $4.15B–$4.20B and adjusted EBITDA outlook to $790M–$800M, reflecting accelerating profitability across its ecosystem. The company generated $286M in quarterly adjusted free cash flow, repurchased $400M in shares during September and October, and retains another $500M in buyback authorization, highlighting improving operating leverage and increasing shareholder returns. 4. President Donald Trump and Vice President JD Vance expressed growing optimism about a potential U.S.–Iran agreement, with Vance saying he feels “good about the prospects” of a deal following several productive discussions with Iranian officials. Vance confirmed that no deadline has been established for resuming military strikes, while Trump said negotiations are “coming together nicely” and suggested that progress toward an agreement has contributed to falling oil prices. Trump also said Iran wants to reach a deal, reiterated Tehran's assurances that it would not develop nuclear weapons, and indicated that the U.S. would refrain from further strikes against Iranian leadership. Meanwhile, Qatari mediators are reportedly traveling to Tehran to meet Foreign Minister Abbas Araghchi and discuss a revised agreement that has been under negotiation for eight days, according to Reuters. However, Iranian state-linked Fars News pushed back against reports of a breakthrough, citing a source who said no meaningful progress has occurred and that Tehran will not move forward until Washington satisfies Iran's seven conditions. 5. The top 10 most active options today by contracts traded were $NVDA with 4.7M contracts, $TSLA with 3.7M contracts, $INTC with 2.1M contracts, $MU with 1.8M contracts, $AMZN with 1.8M contracts, $AAPL with 1.6M contracts, $GOOGL with 1.0M contracts, $AMD with 1.0M contracts, $SPCX with 1.0M contracts, and $ORCL with 768K contracts. 6. Anthropic is reportedly facing pressure from institutional investors to price its upcoming November IPO at a $1.5T–$1.6T valuation, down from earlier expectations approaching $2T, according to the Wall Street Journal. The more cautious outlook follows the recent technology selloff and growing concerns over the sustainability of massive AI infrastructure spending, despite Anthropic reporting $17B in Q3 revenue, up from $11.6B in Q2, even after approximately $600M in pricing reductions and customer discounts. The company has also disclosed an extraordinary $895.4B in combined AI computing purchase and lease commitments, including $447.5B expected before 2031, with most remaining obligations extending through 2045. Anthropic could begin its IPO roadshow next week, with trading potentially starting before Thanksgiving, although the final valuation, offering size, and share price remain undetermined. 7. Marvell $MRVL announced a massive $115B all-stock acquisition of Lumentum $LITE, creating a new powerhouse in AI networking, optical connectivity, and custom silicon. Under the agreement, Lumentum shareholders will receive 4.5 Marvell shares for each Lumentum share, valuing Lumentum at approximately $1,132 per share, a 23.9% premium to its unaffected closing price. Following the transaction, Marvell shareholders will own 67% of the combined company, with Lumentum shareholders owning 33%. The merger combines Marvell's expertise in custom AI chips, switching, and electrical interconnects with Lumentum's leadership in lasers, optical transceivers, and optical circuit switching, positioning the combined business to address an estimated $550B total addressable market. 8. U.S. equity funds recorded $6.7B in net outflows during the week ending October 28, marking their largest weekly withdrawal since mid-September and reversing the $5.1B and $13B in inflows recorded over the previous two weeks. Meanwhile, global equity funds attracted $10.2B, extending their inflow streak to six consecutive weeks, although demand slowed considerably from $25.1B and $19.8B in the preceding weeks. Asian equity funds led global inflows with $9.9B, down from $11.6B the prior week, while European equity funds attracted another $4.5B. 9. Disney $DIS is reportedly preparing to eliminate thousands of jobs as part of a major cost-cutting initiative, with some managers instructed to target 20% in annual cost savings across their operations. The reductions are expected to come from a combination of workforce layoffs and lower operating expenses, with certain business divisions facing deeper cuts than others. Disney, which employed approximately 231,000 people worldwide at the end of its last fiscal year, plans to redirect a portion of the savings toward film and television programming, technology, theme parks, and cruise operations. 10. Bloom Energy $BE and California Resources Corporation $CRC signed a non-binding memorandum of understanding to explore the development of more than 1 GW of power generation capacity in California, combining Bloom's solid-oxide fuel cell technology with carbon capture and storage infrastructure. Under the proposed partnership, Bloom would provide its on-site power generation systems, while CRC's Carbon TerraVault would handle CO2 transportation and permanent underground storage. The projects, being evaluated across Central and Northern California, could supply electricity to AI data centers, utilities, and industrial customers, with the companies estimating that up to 3 million metric tons of CO2 annually could be available for capture and storage. 11. AST SpaceMobile $ASTS and AT&T $T announced the first successful handoff of an active cellular connection between a terrestrial network and a satellite network using an unmodified smartphone, marking a significant milestone for direct-to-device satellite connectivity. The test successfully transferred an active connection between AT&T's ground-based cellular infrastructure and AST SpaceMobile's BlueBird satellites, leveraging networking technology from Ericsson $ERIC and Nokia $NOK. The achievement demonstrates progress toward enabling ordinary smartphones to transition between traditional cell towers and satellite coverage without requiring specialized hardware. AT&T said the next step will involve real-world beta testing ahead of a potential commercial rollout, bringing AST SpaceMobile closer to delivering satellite-based cellular coverage in areas where conventional networks are unavailable. 12. Piper Sandler believes a potential SpaceX $SPCX and Tesla $TSLA merger proposal is now more likely than not, as both companies have reportedly established independent special committees to evaluate a possible combination. The firm expects Elon Musk to retain more than 70% voting control of the combined entity under most potential transaction structures, allowing him to maintain significant influence over the businesses. A merger could bring together Tesla's electric vehicles, autonomous driving, robotics, and energy infrastructure with SpaceX's satellite connectivity, launch operations, and AI computing capabilities, potentially creating one of the world's most vertically integrated technology companies. WALL STREET IS THE GREATEST SHOW ON EARTH.
♥ 68 ⟳ 2 💬 8 👁 15.1k View →
Venu View Profile ↗
Venu Venu @Venu_7_
Since its 2018 IPO, Spotify $SPOT has returned 305%. Revenue grew 255%, from $6B to $21.3B, while annual EPS improved from -$0.50 to $16.28. By 2028, analysts project $28.6B in revenue and $28.60 EPS. A remarkable turnaround in profitability!
♥ 33 ⟳ 3 💬 5 👁 6.0k View →
Venu Venu @Venu_7_
Google $GOOGL is testing key support around $270, near its April 2025 anchored VWAP and March 2026 support. If market weakness continues, a revisit of the 200-week SMA ($204) could offer a long-term opportunity. Not sure if we get there! The last two tests worked well: October 2022 and April 2025.
♥ 58 ⟳ 4 💬 21 👁 9.5k View →
Venu Venu @Venu_7_
While former leaders struggle, a few names are quietly preparing for potential Stage 2 uptrends! Stage 1 bases, institutional accumulation, PEG candles & potential trend reversals. $MIR - Nuclear & radiation safety $FISV - Payments & fintech $GPK - Consumer packaging $WING - Restaurant franchise
♥ 77 ⟳ 11 💬 21 👁 9.6k View →
Venu Venu @Venu_7_
William O’Neil's CAN SLIM philosophy explains why you should continue studying stocks and monitoring potential leaders during market corrections, even when you're holding mostly cash. The important distinction is that looking for opportunities and taking positions are not the same thing. O’Neil emphasized that roughly 3 out of 4 stocks follow the general market direction. Even companies with outstanding earnings and fundamentals can decline during market corrections. But corrections also help reveal the next generation of market leaders. Why staying engaged matters: 1. Future leaders often reveal themselves during corrections. Stocks that decline less than the major indexes, hold key support levels, and maintain strong relative strength may be showing signs of institutional accumulation. 2. Corrections separate strong stocks from weak stocks. When the market eventually recovers, stocks with superior earnings growth, strong relative strength, and constructive bases often emerge as potential leaders. Strong fundamentals alone aren't enough. Price and volume must confirm the story. 3. Build your watchlist before the market turns. If you wait until the indexes have already recovered to start researching companies, you may miss some of the best opportunities. Study earnings growth, industry leadership, relative strength, and developing bases while the market is still correcting. 4. Let the market earn your exposure. O’Neil generally favored waiting for evidence of a confirmed market uptrend before making new purchases. Start with carefully selected positions when conditions improve, and increase exposure gradually as breakouts succeed and your purchases begin working. 5. A follow-through day is important, but not a guarantee. A follow-through day signals a potential change in market direction. However, not every follow-through day leads to a sustained uptrend. Watch whether leading stocks break out successfully, market breadth improves, and institutional buying supports the recovery. The key lesson: Market corrections aren't a reason to stop doing your homework. They're an opportunity to identify potential leaders, study their fundamentals, and monitor their technical strength. You don't have to predict the exact bottom or buy every stock showing relative strength. The next market leaders often begin separating themselves from the crowd before the indexes confirm a new uptrend. Your job is to recognize them early, prepare your watchlist, and act when the evidence supports it.
♥ 8 ⟳ 0 💬 2 👁 1.6k View →
Venu Venu @Venu_7_
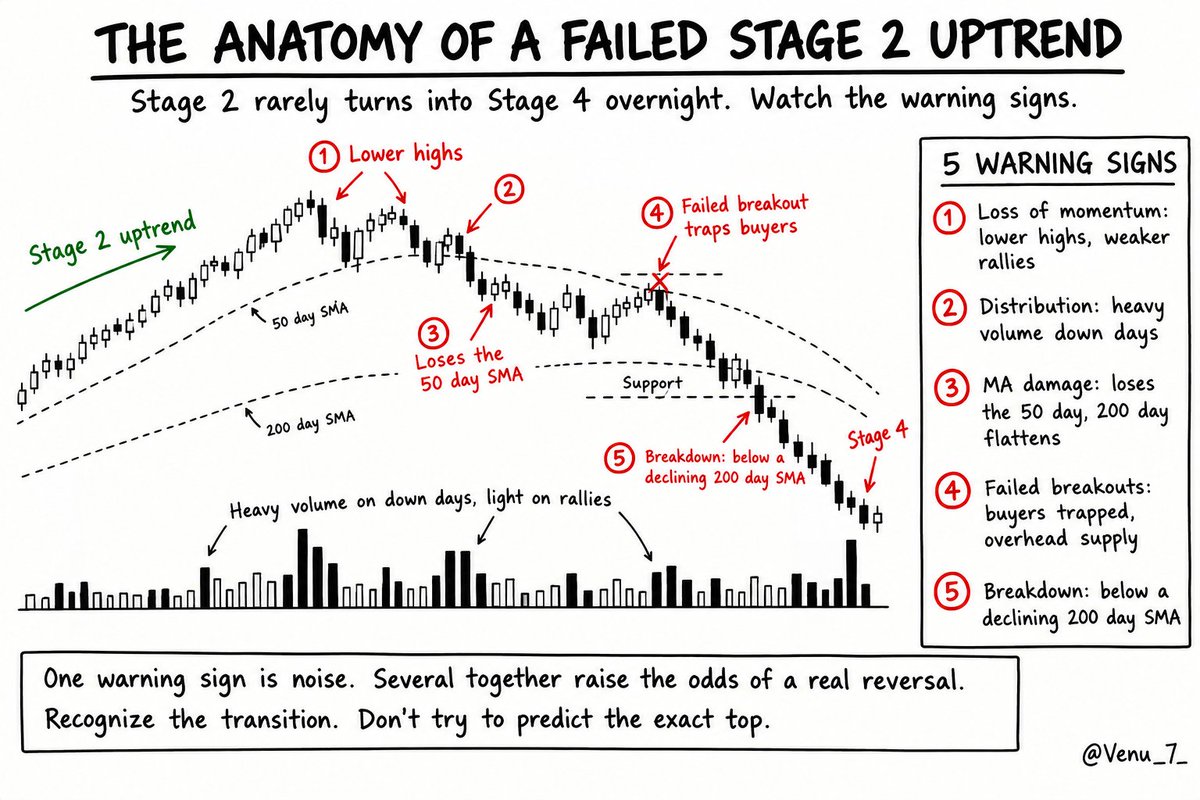
The Anatomy of a Failed Stage 2 Uptrend One of the most important lessons in Stan Weinstein's Stage Analysis is recognizing when a strong uptrend begins to deteriorate. A Stage 2 uptrend doesn't usually turn into Stage 4 overnight. There are often warning signs along the way. 1. Loss of momentum: The stock stops making higher highs, rallies become weaker, and price begins forming lower highs. 2. Distribution: Down days occur on heavier volume while rallies attract weaker volume, suggesting selling pressure is increasing. 3. Moving average deterioration: Price repeatedly loses the 50-day SMA, and the 200-day SMA begins flattening after a sustained advance. 4. Failed breakouts: The stock breaks above resistance but quickly reverses, trapping recent buyers and creating overhead supply. 5. Breakdown: Price loses major support and eventually trades below a declining 200-day SMA, signaling a potential transition toward Stage 4. Not every failed breakout means the uptrend is over. But when multiple warning signs appear together, the probability of a sustained trend reversal increases. The key lesson: Technical deterioration often begins before the long-term trend officially changes. Recognizing that transition matters more than predicting the exact top.
♥ 41 ⟳ 6 💬 13 👁 5.0k View →
Venu Venu @Venu_7_
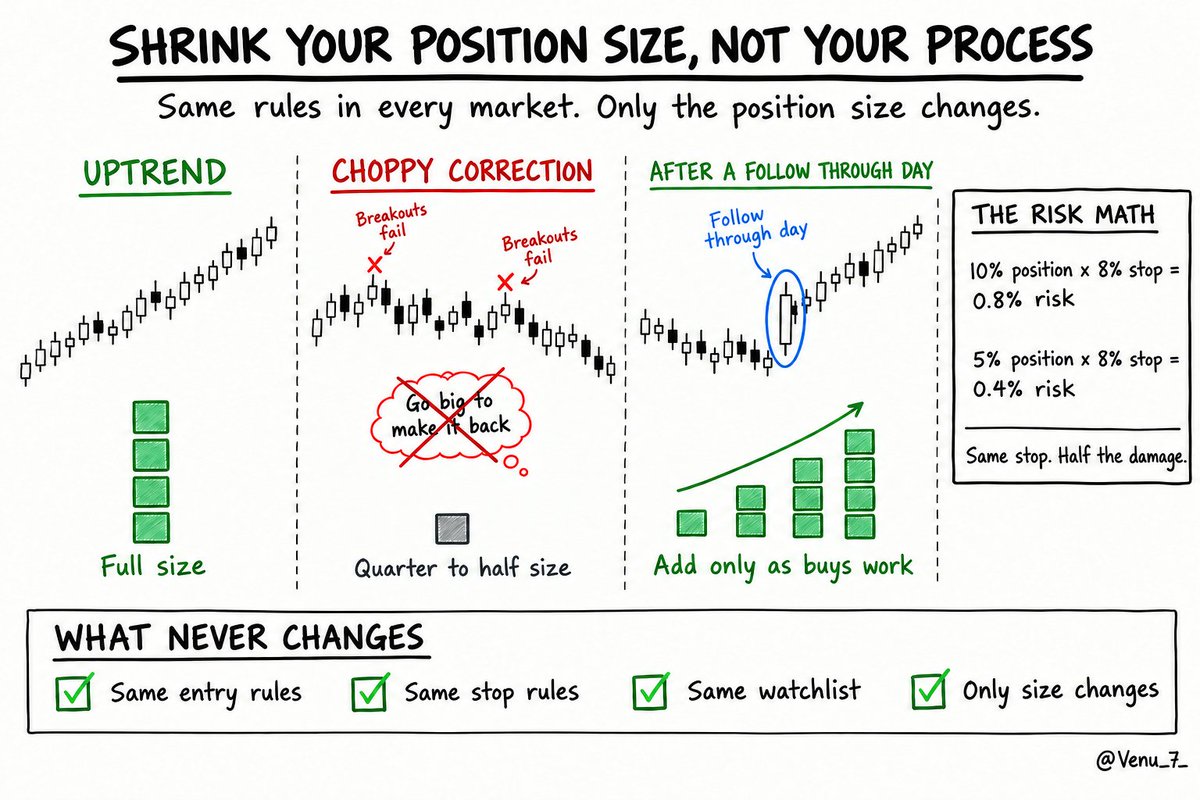
Shrink Your Position Size, Not Your Process. One of the biggest mistakes during market corrections is abandoning a proven framework or increasing position sizes to recover losses. The approach is simple: adjust your exposure to market conditions, not your discipline. 1. Confirmed Uptrend: Normal position sizing when breakouts are working and market leadership is expanding. 2. Choppy Correction: Reduce positions to a quarter or half of normal size. Failed breakouts and increased volatility demand smaller exposure. 3. After a Follow-Through Day: Start small and gradually increase exposure only when your purchases begin working. Here's the risk math: - 10% position × 8% loss = 0.8% portfolio impact. - 5% position × 8% loss = 0.4% portfolio impact. Same percentage loss. Half the portfolio damage. Reducing position size doesn't mean lowering your stock selection standards. Focus on relative strength, healthy price structures, and improving market breadth. If opportunities aren't there, staying in cash is also a valid decision. Your entry rules, exit criteria, and stock selection process should remain consistent regardless of market conditions. A follow-through day doesn't guarantee the correction is over. Let price action and market leadership confirm the improvement. The market will offer new opportunities. Make sure you're in a position to take advantage of them.
♥ 5 ⟳ 0 💬 2 👁 1.6k View →
The Great Mattsby View Profile ↗
The Great Mattsby The Great Mattsby @GreatMattsby
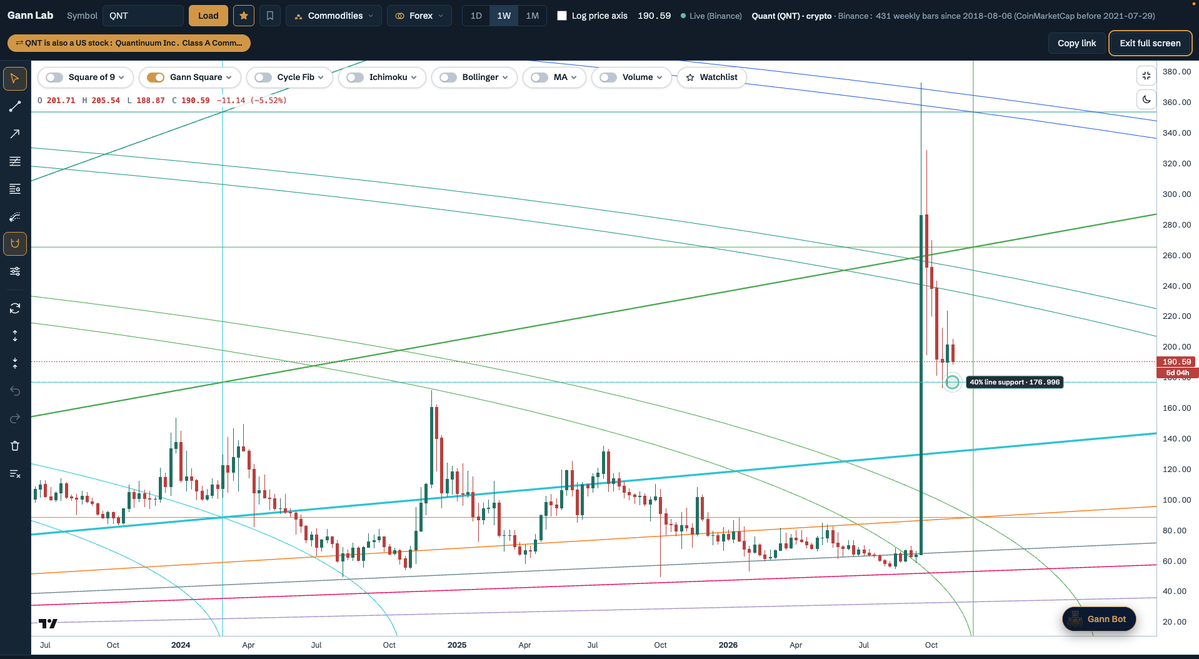
$QNT went from 60 to 370 in one weekly candle. Now it's at 190. Chasing here? Gann Bot says no: 📍 Support zone at 171.61–177.00, about 8% below ⚖️ Buying from here pays less than 1 to 1 ✅ On a dip into that zone, it's about 3.2 to 1 against the 191–194 resistance The bulls aren't done, but the better entry is lower. Would you wait for 177 or buy now?
♥ 45 ⟳ 5 💬 6 👁 6.8k View →
❝ QT Nov 04 · 03:30 SGT 3.7h ago
The Great Mattsby The Great Mattsby @GreatMattsby
$NFLX is about 11% above its best buy zone. I asked Gannbot where the best risk/reward is on my chart: 📍 56.09–56.39: the 1x1 angle (45˚ angle), 40% grid line and 100 SMA all stacked 🎯 First target 63.96 (0.886 cycle fib) ⚖️ About 6 to 1 reward to risk The nearer zone, 57.49–58.58, is about 3.5 to 1. Would you wait or buy here? x.com/GreatMattsby/status/2117681381014…
The Great Mattsby @GreatMattsby
Quoting Nov 04 · 02:12 SGT · 5h ago
What ticker should I run through Gann Bot next? Best reply gets a full breakdown.
Open on X →
♥ 37 ⟳ 4 💬 10 👁 7.2k View →
The Great Mattsby The Great Mattsby @GreatMattsby
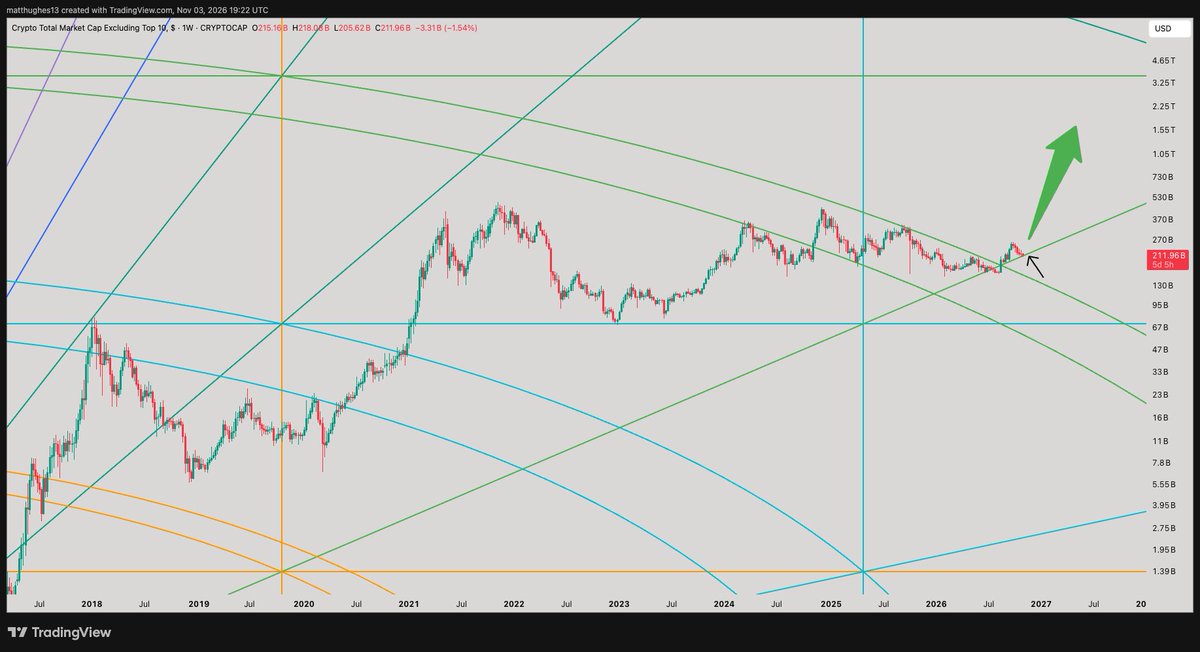
5 of the biggest stocks in America are sitting on a major Gann level right now: $NVDA hit support $AMAT hit support $PANW hit resistance $KKR hit resistance $OXY hit support Scanned 2,500+ stocks and 250 coins. No hand-drawn lines, just math. 👇
♥ 19 ⟳ 3 💬 7 👁 3.3k View →
❝ QT Nov 03 · 21:40 SGT 9.5h ago
The Great Mattsby The Great Mattsby @GreatMattsby
Being positioned for massive upside is the only way #crypto x.com/NCashOfficial/status/211748264139…
Nick | Crypto Crusader @NCashOfficial
Quoting Nov 03 · 13:02 SGT · 18h ago
I never would have thought that we would get to this point in the crypto market. What am I talking about? I am talking about the fact that we are watching as DeFi expands on the $XRP ledger for the first time in 14 years. Ripple is becoming a bank at the same time that major banking partnerships just got announced with XRP at the core. We have the largest XRP treasury company moving rapidly to expand the ecosystem, scale institutional adoption of the ledger and acquire more XRP. The DTCC just went live with their $30T tokenization system (part of the $114T total) with public blockchains scheduled for 2027. Wall Street is moving rapidly to tokenize at the same time that banks around the world are actively tokenizing. The US Government is actively positioning dollar denominated stablecoins as the answer to foreign nations dumping US debt. US regulators are all actively promoting digital asset technology i.e. the SEC, CFTC, OCC, not to mention support from the FED & FDIC. All of this is happening, but because the charts aren't pumping it apparently all means nothing and EVERYONE is extremely upset pointing the finger at anyone possible. The sentiment is just abysmal even though everything we have been waiting for is happening in front of us. The next move to the upside will be very painful, because most of retail won't be positioned for it because they are too busy complaining about discounted opportunities. It really is unfortunate.
Open on X →
♥ 20 ⟳ 0 💬 2 👁 1.9k View →
❝ QT Nov 03 · 07:48 SGT 23h ago
The Great Mattsby The Great Mattsby @GreatMattsby
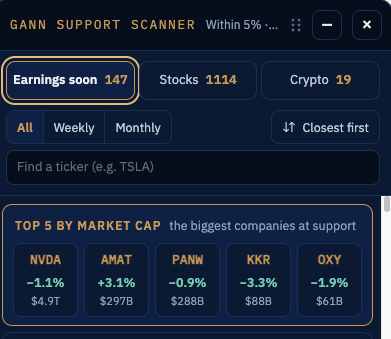
Dec 2023: everyone was calling for $AAPL 120, $SPY 320, $NVDA 350. I said the math says higher. $SPY 750. $NVDA 700–1200. $AAPL 350. Today: $AAPL $330 $SPY $750. $NVDA $200 [which is $2000 split-adjusted price]. I've been bullish for years. Not because I'm lucky, because I stopped trying to time every top and bottom. The people waiting for the perfect entry are still waiting. Time in the market > timing the market. x.com/GreatMattsby/status/1736967959107…
The Great Mattsby @GreatMattsby
Quoting Dec 19 · 12:33 SGT · 1050d ago
All charts below are telling a different story. $AAPL still has room to run to $350 $SPY has room to go to $750 $NVDA has room to go to $700 -$1200 $AMD has room to go to $240 And so on.... This is all complete historical data showing all the previous support and resistance zones. Based off this math they are going higher, not lower. What kind of math did you use when you chose your price targets?
Open on X →
♥ 20 ⟳ 4 💬 7 👁 3.2k View →
Freedom By 40 View Profile ↗
Freedom By 40 Freedom By 40 @Freedom_By_40
I just realized I could've been posting all my shit in mining mafia during this drawdown instead of posting out in the wild with potential gremlins and haters. Nothing against mining mafia, I think its great and I am a member. But I think I will still post out in the wild.
♥ 36 ⟳ 2 💬 4 👁 2.4k View →
Moe View Profile ↗
❝ QT Nov 04 · 06:00 SGT 1.2h ago
Moe Moe @Crypto_Moe84
These are the comments which why i will close soon the doors my friends... unfortunately I said Q3 2026 will be bullish. I said Q4 2026 will be bullish. I said 2027 will be a great year which timeframes did i push back? I dont like fake media. Dont make me angry I dont play your weekly Price-Action.... For your information a great year 2027 doesnt mean you will see no corrections...lol -- Of course there will be extreme corrections but overall it will be a great year. Sorry friends we are not the same. Your emotions are to much guided by LTF Price action
Dub Cap @DubCap1
Quoting Nov 04 · 05:34 SGT · 1.6h ago
@Crypto_Moe84 I am a fan of following you, but I feel like your timeframe keeps getting pushed back.
Open on X →
♥ 73 ⟳ 4 💬 16 👁 3.0k View →
❝ QT Nov 04 · 05:03 SGT 2.1h ago
Moe Moe @Crypto_Moe84
Moe @Crypto_Moe84
Quoting Oct 22 · 04:13 SGT · 13d ago
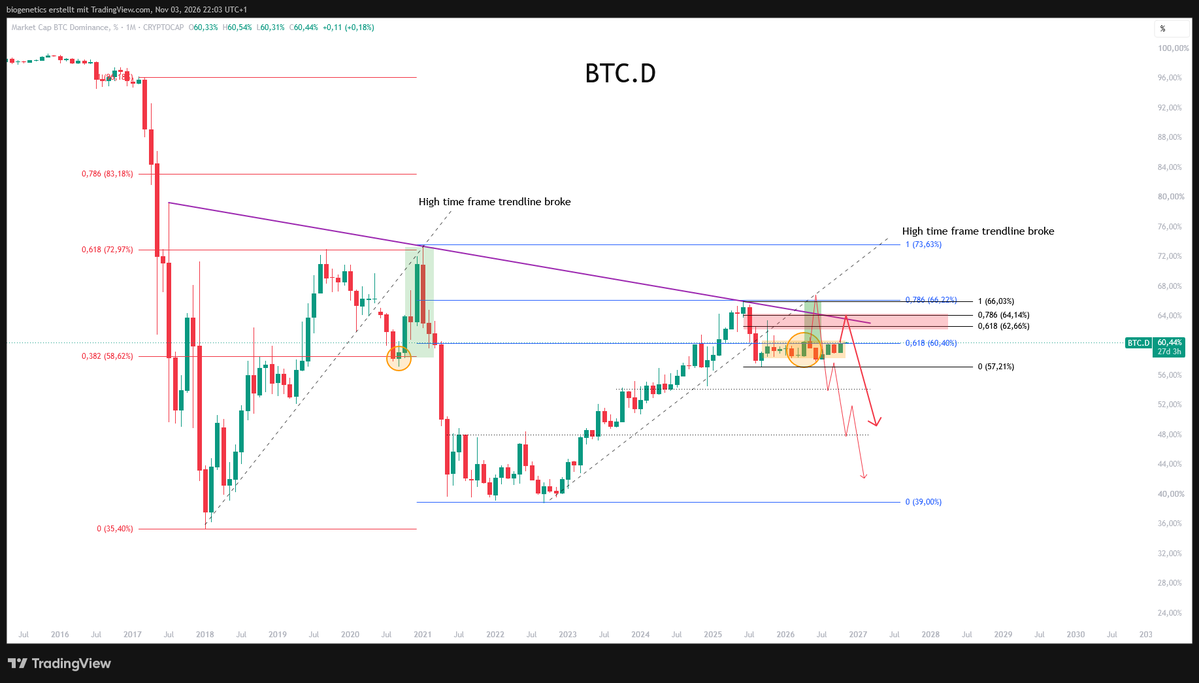
$BTC.D I know bros $BTC.D isnt a easy chart to read on LTF. We all know what will happen to this chart HTF. The question is just if we go up before the drop or not. Its just LTF-Noise If we go up - I expect a zone of approx. 63%-64% before the drop. It will be just a fake-out, out of this range to then drop hard. Like this Soccer-Trick. Trick left then go right Lets see lets see I wouldnt be surprised if we close 2026 red. But what you can see clearly is 2027 THIS BABY IS GOING TO DIE ... this is what is important for us ... all other stuff is LTF-NOISE
Open on X →
♥ 91 ⟳ 11 💬 3 👁 3.8k View →
MarketMaestro View Profile ↗
❝ QT Nov 04 · 07:01 SGT 9m ago
MarketMaestro MarketMaestro @MarketMaestro1
$SPY $QQQ What if I told you that we might be in the exact same situation as 1997 right now... What would you think? twitter.com/ZaStocks/status/21176028836…
Za @ZaStocks
Quoting Nov 03 · 21:00 SGT · 10h ago
In 1998 the Nasdaq dropped 30%. Then it ran almost 300% before topping out in early 2000. Nobody knows what happens from here but it’s worth remembering that the biggest 18 month rally in market history came after a period of major volatility, uncertainty, and fear.
Open on X →
♥ 7 ⟳ 0 💬 2 👁 1.4k View →
MarketMaestro MarketMaestro @MarketMaestro1
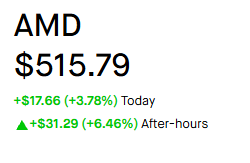
$AMD 😍 AMD Non-GAAP EPS of $2.09 beats by $0.15, revenue of $13.38B beats by $290M Nov 03, 2026 Q3 Non-GAAP EPS of $2.09 beats by $0.15. Revenue of $13.38B (+44.6% Y/Y) beats by $290M. “We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year,” said Dr. Lisa Su, AMD chair and CEO. “Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production. With our leadership product portfolio and deep customer and supply chain relationships, we are confident in our ability to sustain very strong revenue growth and expanding profitability over the coming years.”“Third quarter revenue grew 45% year-over-year to a record $13.4 billion, while non-GAAP earnings per share grew 74%, demonstrating the significant operating leverage in our business model as our Data Center business drives scale,” said Jean Hu, AMD executive vice president, chief financial officer and treasurer. “Our fourth-quarter outlook reflects accelerating revenue and earnings growth, driven by strong demand across our Data Center portfolio.” For the fourth quarter of 2026, AMD expects revenue to be approximately $17 billion, plus or minus 3% vs consensus of $16.14B. The mid-point of the revenue range represents year-over-year growth of approximately 66% and a sequential increase of approximately 27%. Non-GAAP gross margin is expected to be approximately 55%.
♥ 16 ⟳ 3 💬 4 👁 3.1k View →
MarketMaestro MarketMaestro @MarketMaestro1
$NVTS Navitas Semiconductor GAAP EPS of -$0.14 misses by $0.05, revenue of $13.99M beats by $0.49M Nov 03, 2026 Q3 GAAP EPS of -$0.14 misses by $0.05. Revenue of $13.99M (+38.4% Y/Y) beats by $0.49M. Also based on our guidance, we anticipate achieving revenue growth of 7% for the full year 2026 with our core high-power business continuing to deliver triple-digit growth, even with our mobile and low-end consumer business dropping to effectively zero after representing a large majority of total revenue last year.
♥ 4 ⟳ 1 💬 1 👁 3.0k View →
MarketMaestro MarketMaestro @MarketMaestro1
$XYZ Block Non-GAAP EPS of $1.13 beats by $0.10, revenue of $6.72B beats by $120M Nov 03, 2026 Q3 Non-GAAP EPS of $1.13 beats by $0.10. Revenue of $6.72B (+10.0% Y/Y) beats by $120M. Shares +6%.
♥ 2 ⟳ 0 💬 1 👁 2.8k View →
MarketMaestro MarketMaestro @MarketMaestro1
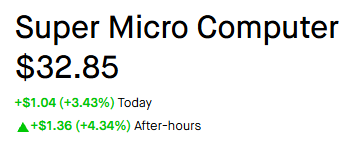
$SMCI Super Micro Computer Non-GAAP EPS of $1.81 beats by $0.58, revenue of $19.95B beats by $3.69B Nov 03, 2026 Q1 Non-GAAP EPS of $1.81 beats by $0.58. Revenue of $19.95B (+299.0% Y/Y) beats by $3.69B. “Supermicro’s transformation into a Total AI and IT Datacenter Solution provider continues to accelerate, delivering record revenue of $19.9 billion for the first quarter fiscal 2027,” said Charles Liang, Founder, President, and CEO of Supermicro. “DCBBS is driving significant value for our customers—from gigawatt-scale datacenters down to single-container PODs—which, including our expanding software, proactive service, and networking solutions, is enhancing profitability and long-term shareholder value. Through key enterprise partnerships and expanding global production capacity, we are making AI infrastructure faster to deploy, superior up-time and more cost-effective for our customer base.”The Non-GAAP gross margin for the first quarter of fiscal year 2027 was 12.8% with adjustments for stock-based compensation expense of $8 million. The Non-GAAP diluted net income per common share for the first quarter of fiscal year 2027 was $1.81.As of September 30, 2026, total cash and cash equivalents was $6.9 billion and total bank debt and convertible notes were $8.6 billion. Business OutlookThe Company expects net sales in the range of $19.5 billion and $21.5 billion for the second quarter of fiscal year 2027 ending December 31, 2026 vs consensus of $17.51B, GAAP net income per diluted share of $1.59 to $1.83 and non-GAAP net income per diluted share of $1.66 to $1.90 vs consensus of $1.14.For fiscal year 2027, the Company expects net sales in the range of $72.0 billion to $82.0 billion vs consensus of $70.27B
♥ 3 ⟳ 0 💬 1 👁 2.9k View →
MarketMaestro MarketMaestro @MarketMaestro1
$DUOL Duolingo GAAP EPS of $0.54 misses by $0.02, revenue of $309M beats by $5.97M Nov 03, 2026 Q3 GAAP EPS of $0.54 misses by $0.02. Revenue of $309M (+13.7% Y/Y) beats by $5.97M. Shares +12%.
♥ 5 ⟳ 2 💬 4 👁 2.8k View →
MarketMaestro MarketMaestro @MarketMaestro1
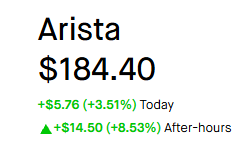
$ANET 😍 Arista Networks Non-GAAP EPS of $1.20 beats by $0.12, revenue of $3.66B beats by $330M Nov 03, 2026 Q3 Non-GAAP EPS of $1.20 beats by $0.12. Revenue of $3.66B (+58.4% Y/Y) beats by $330M. Delivered total revenues in Q3 2026 of approximately $3.66 billion, exceeding guidance of $3.3 billion while growing 58.5%, the highest year-over-year revenue growth since our IPO. For the fourth quarter of 2026, we expect:Revenue of $3.9 - $4.0 billion vs $3.33B consensus Non-GAAP operating margin of 48 - 49%; and Non-GAAP diluted net income per share of $1.26 - $1.30.
♥ 2 ⟳ 0 💬 2 👁 2.8k View →
MarketMaestro MarketMaestro @MarketMaestro1
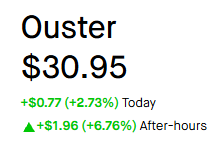
$OUST 😍 Ouster GAAP EPS of -$0.20 beats by $0.04, revenue of $59M beats by $2.73M Nov 03, 2026 Q3 GAAP EPS of -$0.20 beats by $0.04. Revenue of $59M (+49.3% Y/Y) beats by $2.73M. Adjusted EBITDA loss of $3 million, an improvement of $5 million year over year and an improvement of $1 million sequentially. Cash, cash equivalents, restricted cash, and short-term investments of $421 million as of September 30, 2026. Fourth Quarter 2026 Outlook:For the fourth quarter of 2026, Ouster expects to achieve $61 million to $64 million vs. a consensus of $62.03M in total revenue.
♥ 4 ⟳ 0 💬 1 👁 3.2k View →
MarketMaestro MarketMaestro @MarketMaestro1
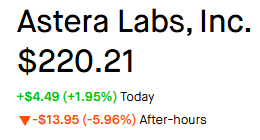
$ALAB Astera Labs Non-GAAP EPS of $1.32 beats by $0.13, revenue of $584.9M beats by $34.1M Nov 03, 2026 Q3 Non-GAAP EPS of $1.32 beats by $0.13. Revenue of $584.9M (+153.6% Y/Y) beats by $34.1M. Fourth Quarter of Fiscal 2026 Financial OutlookBased on current business trends and conditions, Astera Labs estimates the following:GAAP Financial Outlook:Revenue within a range of $730 million to $750 million vs consensus of $655.71M GAAP gross margin of approximately 72% GAAP operating expenses within a range of approximately $273 million to $279 million GAAP tax rate of approximately 20% GAAP diluted net income per share of approximately $1.13 to $1.17 on weighted-average diluted shares outstanding of approximately 187 million Non-GAAP Financial Outlook(2):Non-GAAP gross margin of approximately 72% Non-GAAP operating expenses within a range of approximately $194 million to $200 million Non-GAAP tax rate of approximately 12% Non-GAAP diluted net income per share of approximately $1.62 to $1.66 vs consensus of $1.42 on weighted-average diluted shares outstanding of approximately 187 million
♥ 5 ⟳ 1 💬 2 👁 3.1k View →
MarketMaestro MarketMaestro @MarketMaestro1
$AAPL After breaking above the BoS zone, it ran into the neckline, Fibonacci resistance, and the correction band before experiencing a liquidity sweep. It could look for a swing low, and that would present an opportunity
♥ 7 ⟳ 2 💬 4 👁 3.8k View →
MarketMaestro MarketMaestro @MarketMaestro1
$BE Bloom Energy jumps 9% after Barclays upgrade, California power development deal Nov 03, 2026 Bloom Energy (BE) popped 8.9% in Tuesday's trading after Barclays upgraded the stock and the company unveiled a potential large-scale power partnership with California Resources Corp. to evaluate the potential development of at least 1 GW of fuel cell power generation paired with carbon capture and storage in the state. Barclays upgraded Bloom (BE) to Overweight from Equal Weight with a $289 price target, saying demand appears to be inflecting more sharply than previously expected, as customer deposits increased from $78M in year-end 2025 to $661M in Q3 2026, including a ~$300M sequential increase in Q3 alone. Importantly, the change in the balance understates gross deposits received to the extent deposits associated with shipments were released into revenue during the quarter, according to Barclays analyst Christine Cho; assuming customers generally provide an upfront deposit of ~10% of contract value, the ~$300M net increase alone could imply at least ~$3B of underlying contract value for Bloom (BE), Cho said. "Taken together, the increase in customer deposits, accelerated manufacturing expansion, and significant new supplier commitments suggest to us that management has gained materially greater confidence in the forward demand pipeline than we had previously assumed," Cho wrote.
♥ 13 ⟳ 2 💬 4 👁 4.2k View →
MarketMaestro MarketMaestro @MarketMaestro1
$UPST Upstart GAAP EPS of $0.33 beats by $0.10, revenue of $371M beats by $7.3M; updates FY outlook Nov 03, 2026 Q3 GAAP EPS of $0.33 beats by $0.10. Revenue of $371M (+33.9% Y/Y) beats by $7.3M. Originations: $4.1 billion, up 44% year-over-year (“YoY”). A record 574,089 loans originated, up 34% YoY. Contribution Profit: All-time high of $218 million, up 48% YoY. Contribution Margin was 60%, versus 57% in Q3 2025. Adjusted EBITDA: $89.3 million, up 26% YoY from $71.2 million in Q3 2025. Adjusted EBITDA Margin was 24%, down from 26% in Q3 2025. Financial OutlookFor full-year 2026, Upstart expects:Revenue From Fees of approximately $1.32 billion Total Revenue of approximately $1.35 billion vs. consensus of $1.42B Adjusted EBITDA (Margin % of Total Revenue) of approximately $260 million (19%) Upstart reports Q3 earnings above expectations; guides on 2026 with caution Nov 03, 2026 Upstart Holdings (UPST) reported strong third-quarter earnings exceeding analyst estimates, with a cautious outlook for the full-year considering interest rates and borrower health. Diluted net income per share rose to $0.33 during Q3 from $0.23 in the same period a year ago, exceeding the Visible Alpha consensus of $0.22. Net income increased to $36.6M with a 10% margin, against 6.59% expected. Adjusted EBITDA came in at $89.3M, vs. the $81.45M consensus. Total revenue increased 34% year-over-year to $371M, above the average analyst estimate of $364.56M. Revenue from fees increased 41% to a record $364M, vs. $340.98M estimated. Contribution profit hit an all-time high of $218.18M, up 48% from the previous year. Analyst estimates were $189.65M. Loans on the balance sheet declined 4.8% to $19.534B. "It's long been our strategy to fund the vast majority of our loans with third-party capital," CEO Paul Gu told Seeking Alpha. "We want to be really efficient with equity capital, and this was a quarter where we did that. We lowered the percent of all loans that are on the balance sheet. We also lowered the percent of equity that's required to fund the business through any of our funding partnerships," said the CEO. "We view those as great wins and moves in the right direction, and there's more to go there. That basically is just a function of the fact that we are growing our third-party capital partnerships, and those partners are signing up and growing and renewing," said Gu. Originations were up 44% from the prior year to $4.1B. For the full-year 2026, Upstart revised its revenue from fees guidance higher to $1.32B from $1.30B, in line with the Visible Alpha consensus of $1.32B. Revenue guide was lowered to $1.35B from 1.40B, vs. the $1.42B consensus. Adjusted EBITDA is now expected at $260M, compared to the previous outlook of $294M and the $290.35M consensus. "Our business is sensitive to borrower health and interest rates," said Gu on delinquencies. "Borrower health, we quantified using the Upstart Macro index called UMI. Earlier this year, we had shared that we forecast 2026 UMI of between 1.4 and 1.5. We've seen UMI take up 14 points over the course of the year, which is a significant increase in the stress of the underlying consumer." "That's closely related to the fact that we've had six straight months here where inflation has outpaced wage growth, and so ordinary Americans are seeing their real wages declining. Whenever that happens, people who are net users of credit are going to be in more stress." "There's also an interest rate story, which is pretty self-explanatory," said the CEO. "The health of the American borrower is under more financial stress than they were before, and in light of that, we are taking a little bit more of a cautious view towards what we expect going forward," said the CEO. "We're really optimistic on a multi-year basis, time frame here, and, just want to be cognizant and thoughtful about where the macro is today," said Gu.
♥ 2 ⟳ 0 💬 1 👁 1.3k View →
MarketMaestro MarketMaestro @MarketMaestro1
$TLN Talen Energy reports mixed Q3 results; reaffirms FY26 outlook Nov 03, 2026 Q3 GAAP EPS of $2.88 misses by $5.72. Revenue of $1.33B (+63.8% Y/Y) beats by $40M. Third quarter Adjusted EBITDA of $669 million and Adjusted Free Cash Flow of $433 million. Announced $1.5 billion accelerated share repurchase program (“ASR”) expected to be complete by the end of the first quarter 2027. Upsized share repurchase program (“SRP”) to $3.0 billion through December 31, 2028 (including the ASR). Reaffirming 2026 Adjusted EBITDA and Adjusted Free Cash Flow guidance ranges to $2,050 million - $2,200 million and $1,225 million - $1,325 million, respectively. Introducing 2027 Adjusted EBITDA and Adjusted Free Cash Flow guidance ranges of $2,500 million - $2,850 million and $1,500 million - $1,750 million, representing approximately 26% and 27% growth at the midpoints compared with 2026 guidance.
♥ 0 ⟳ 0 💬 1 👁 1.1k View →
MarketMaestro MarketMaestro @MarketMaestro1
$DOCN DigitalOcean Non-GAAP EPS of $0.45 beats by $0.13, revenue of $321M beats by $14.26M Nov 03, 2026 Q3 Non-GAAP EPS of $0.45 beats by $0.13. Revenue of $321M (+39.6% Y/Y) beats by $14.26M. Raising Q4 2026 exit revenue growth outlook to 44-45% and increasing expected 2027 revenue growth to 60%+ Million+ Dollar Customer ARR grew 273% year-over-year to $386 millionAI Customer ARR grew 288% year-over-year to $376 millionRecord $160 million in incremental ARR DigitalOcean is providing guidance for the fourth quarter ending December 31, 2026 as follows:Total revenue of $348 to $351 million vs $306.74M consensus, up 44% to 45% year-over-year. Adjusted EBITDA margin of 42% to 43%. Non-GAAP diluted net income per share of $0.30 to $0.32 vs $0.32 consensus Fully diluted weighted average shares outstanding of approximately 128 to 129 million shares. For the full year 2026, we now expect:Total revenue of $1.208 to $1.211 billion, up approximately 34% year-over-year. Adjusted EBITDA margin of 41% to 42%. Adjusted free cash flow margin in the range of 20% to 22% of revenue. Non-GAAP diluted net income per share of $1.60 to $1.62 Fully diluted weighted average shares outstanding of approximately 122 to 123 million shares. Digital Ocean slides even as it ups outlook, reports strong Q3 results Nov 03, 2026 Digital Ocean (DOCN) shares erased earlier gains and fell more than 7% in premarket trading on Tuesday even as the cloud computing firm reported better-than-expected results and upped its outlook. For the period ending Sept. 30, Digital Ocean earned an adjusted $0.45 per share as revenue soared 39.6% year-over-year to $321M. Analysts had expected the company to earn an adjusted $0.32 per share on $306.7M in revenue. “Revenue growth accelerated year-over-year to 40%, our fifth consecutive quarter of acceleration, and we added a record $160 million of ARR,” said Paddy Srinivasan, CEO of DigitalOcean, in a statement. “The center of gravity in AI has shifted from people chatting with models to agents doing work, and agents need a different kind of cloud: one where inference, agent runtime, data, and learning operate as a single loop to enable agents to recursively self improve. We built that cloud, and the most sophisticated AI natives are building on it.” Looking to the fourth quarter, Digital Ocean now expects revenue growth to be between 44% and 45%, with revenue between $348M and $351M. Analysts had expected $306.74M in revenue. Adjusted earnings are forecast to be between $0.30 and $0.32, compared to the $0.32 estimate. For the full-year, the company now expects total revenue to be between $1.208B and $1.211B, up approximately 34% year-over-year and above the $1.18B consensus estimate. Adjusted earnings are forecast to be between $1.60 and $1.62 per share. The company also now expects 2027 revenue growth to be at least 60%. Digital Ocean will host a conference call at 8:00 a.m. ET to discuss its results.
♥ 0 ⟳ 0 💬 1 👁 1.3k View →
MarketMaestro MarketMaestro @MarketMaestro1
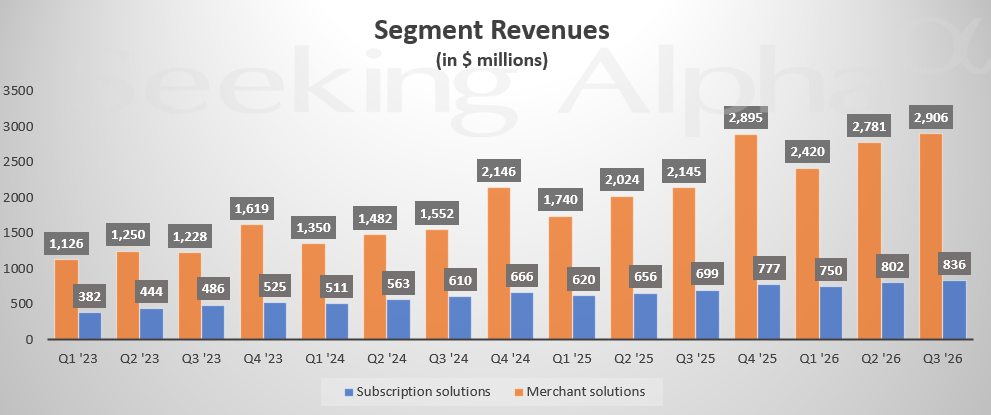
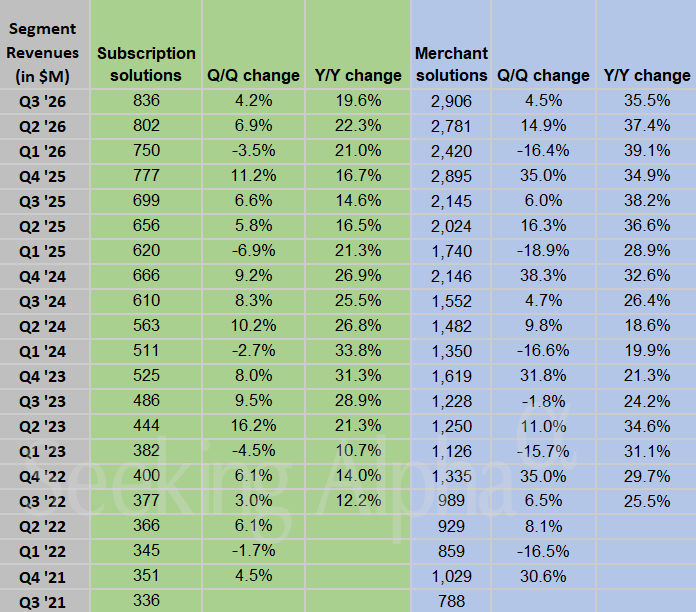
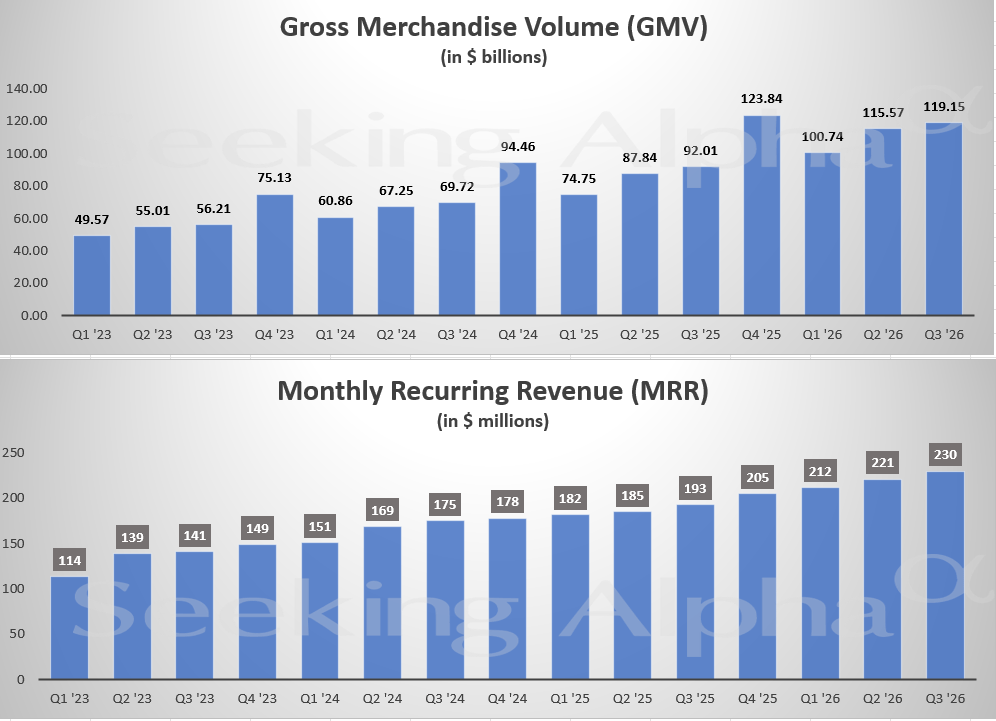
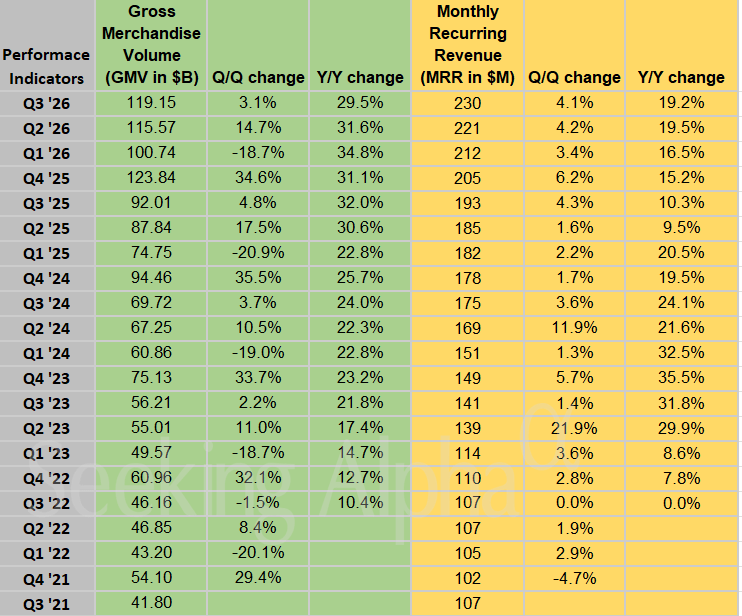
$SHOP Shopify Inc Non-GAAP EPS of $0.49 beats by $0.03, revenue of $3.74B in-line Nov 03, 2026 Q3 Non-GAAP EPS of $0.49 beats by $0.03. Revenue of $3.74B (+31.7% Y/Y) in-line. For the fourth quarter of 2026, we expect: Revenue to grow at a low-thirties percentage rate on a year-over-year basis; Gross profit dollars to grow at a high-twenties percentage rate on a year-over-year basis; Operating expenses as a percentage of revenue to be 29% to 30%; Stock-based compensation to be $155 million; and Free cash flow margin to be consistent with the fourth quarter of 2025. Shopify slides in early investor reaction to a slight GMV miss Nov 03, 2026 Shopify (SHOP) fell sharply on Tuesday after reporting revenue jumped 31.7% in Q3 to $3.74B to match the consensus estimate of analysts. "Shopify is uncommonly good at operating in two realities at the same time: the world our merchants exist in today, and the one they are moving towards. Q3 is the perfect example," updated President Harley Finkelstein. The Ottawa-based company reported gross merchandise volume was up 30% to $119.2B to fall slightly short of the consensus estimate for $120.1B. Monthly recurring revenue improved to $230 from $193 in the same quarter a year ago. Free cash flow was $816M, and free cash flow margin was 22% of sales, up from 18% a year ago. Operating income was $568M vs. $343M a year ago. Net income rose to $462M from $264M a year ago. Notably, Shopify (SHOP) disclosed a 3.3X boost in orders originating from AI searches during the quarter. "Delivering these results at our scale speaks to the strength of our model, our multiple growth drivers, and our expanding addressable market," highlighted CFO Jeff Hoffmeister, Looking ahead, Shopify (SHOP) expects Q4 revenue to grow at a low-thirties percentage rate on a year-over-year basis and gross profit dollars to grow at a high-twenties percentage rate on a year-over-year basis. Shares of Shopify (SHOP) were down 15.3% in the early investor reaction to the earnings update. Shopify in Charts: Merchant solutions sustain over 30% growth in Q3
♥ 3 ⟳ 0 💬 1 👁 1.4k View →
❝ QT Nov 03 · 07:33 SGT 23h ago
MarketMaestro MarketMaestro @MarketMaestro1
$QQQ has experienced a liquidity sweep. It occurs when the BoS zone breaks in the opposite direction, triggering a search for a new swing low! I marked the previous liquidity sweep with the red arrow. Now the index will look for its swing low zone. Not every liquidity sweep has to be the same depth
MarketMaestro @MarketMaestro1
Quoting Oct 22 · 21:50 SGT · 12d ago
This is from last week 👇 twitter.com/MarketMaestro1/status/21131…
Open on X →
♥ 0 ⟳ 0 💬 1 👁 1.0k View →
MarketMaestro MarketMaestro @MarketMaestro1
$SKHY 000660 🇰🇷 Since SKHY has a very limited chart history, it’s worth looking at 000660. It could work through this period by moving sideways, as illustrated by my black candle projection. The duration of that projection could extend or shorten depending on overall market conditions
♥ 5 ⟳ 2 💬 3 👁 1.4k View →
Banana3 View Profile ↗
❝ QT Nov 03 · 22:30 SGT 8.7h ago
Banana3 Banana3 @Banana3Stocks
$SPY $QQQ Happy Election Day for those that celebrate 🎉 Interesting results below on a good sample size of around 1700 people Let’s see what happens twitter.com/banana3stocks/status/211694…
Banana3 @Banana3Stocks
Quoting Nov 02 · 01:42 SGT · 2d ago
$SPY $QQQ Which situation is most likely? Group A) If the Democrats win the House & Senate markets will… Group B) If the Republicans win the House & Senate markets will…
Open on X →
♥ 19 ⟳ 2 💬 7 👁 5.9k View →
❝ QT Nov 03 · 22:16 SGT 8.9h ago
Banana3 Banana3 @Banana3Stocks
$QQQ Unless this fully fades again, they’re trapped 🤷‍♂️ twitter.com/banana3stocks/status/211734…
Banana3 @Banana3Stocks
Quoting Nov 03 · 03:58 SGT · 1d ago
$QQQ Bear Trap 🪤 The Banana325SMA is $650 on the Q’s as the downside bogie, but I think record deleveraging leads to a string bounce soon In the meantime I’m mixing in names that are working like $MCD $RIVN $RKT and several others, while buying the dips in the better AI names $NVDA $AVGO $MRVL $DELL (GARP) and $AMZN $TSLA Also like $BA at these levels Not financial advice!
Open on X →
♥ 7 ⟳ 0 💬 1 👁 1.6k View →
C View Profile ↗
Charting Guy @ChartingGuy
if democrats sweep, expect a further dip in markets slightly below the recent lows not as deep and brutal as bears want and should be over with within 2 weeks or less then we end the month smacking highs if republicans win the senate, that rally can start now the end result is the same for me markets higher by end of month, end of year and in 6 months and 12 months and beyond bears are gay either way
♥ 144 ⟳ 4 💬 8 👁 7.1k View →
❝ QT Nov 03 · 21:39 SGT 9.5h ago
Charting Guy @ChartingGuy
last minute midterm lies? or finally a good decision from this goofy administration? twitter.com/wallstengine/status/2117612…
Wall St Engine @wallstengine
Quoting Nov 03 · 21:37 SGT · 9.6h ago
TRUMP SAYS THE US WILL STOP ITS $4 BILLION A YEAR IN MILITARY AID TO ISRAEL AT THE END OF 2026 "We've already agreed that by the end of this year we won't be paying Israel," Trump told Fox News, saying he and Netanyahu made the deal months ago and that Israel no longer needs it. Israel will still have the option to buy US weapons if the need to, he said.
Open on X →
♥ 18 ⟳ 0 💬 7 👁 1.9k View →
❝ QT Nov 03 · 19:04 SGT 12h ago
Charting Guy @ChartingGuy
and again 3 hours ago this is a rare signal and it flashing this much is signaling that it is accumulation time. each flash has been accompanied by a local low that could’ve made for a good trade or an accumulation spot 😴 twitter.com/chartingguy/status/21173423…
Charting Guy @ChartingGuy
Quoting Nov 03 · 03:45 SGT · 1d ago
Open on X →
♥ 28 ⟳ 0 💬 2 👁 1.8k View →
↑